Term Life Insurance Conversion: 12 Smart Steps Before Your Deadline Expires
Term life insurance conversion may allow an eligible term policy to be exchanged for permanent life insurance without new evidence of insurability. That feature can become valuable when health has changed, long-term protection is still needed or the original level-premium term is approaching its end. It is not automatic, free or necessarily the best choice for every household.
Conversion rules come from the contract. Deadlines, eligible permanent products, maximum amounts and age restrictions vary by carrier and policy. The new premium will generally be higher because permanent insurance is designed for longer-lasting coverage and the premium is based on the insured’s age when conversion occurs.
The right way to evaluate term life insurance conversion is to begin early, request written information and compare it with other available choices. Waiting until the final days can limit the time available to understand costs, product features and the consequences of letting a valuable contractual right expire.
1. Understand What Term Life Insurance Conversion Means
A term policy provides a death benefit for a specified period when required premiums are paid and other contract conditions are satisfied. Many policies also contain a provision allowing some or all of the coverage to be converted to an eligible permanent policy during a stated conversion period.
The key feature of term life insurance conversion is that the insured may not have to provide new evidence of insurability. In practical terms, the conversion may not require a new medical examination or updated health qualification. The insurer still applies the contract’s administrative rules, product availability and premium rates.
Conversion is not the same as extending the old term premium. The term contract is exchanged, in whole or in part, for permanent coverage. The new policy has its own premiums, guarantees, charges, values and limitations. Read both the conversion provision and the proposed permanent-policy materials.
2. Locate the Exact Conversion Deadline
Do not assume the conversion deadline is the same as the end of the level-premium term. Some policies end the conversion right earlier, restrict it at a specified age or offer different products during different conversion periods.
Check the original contract, amendments, endorsements and annual notices. Ask the insurer to confirm the final date in writing. If an agent provides a date, verify it directly with the carrier and retain the response.
A term life insurance conversion review should begin months—not days—before the deadline. Applications, signatures, illustrations and premium arrangements may require time. A calendar reminder one year before the deadline, followed by reminders at six and three months, can help prevent an accidental loss of options.
3. Confirm How Much Coverage Can Be Converted
Some contracts permit conversion of the full death benefit, while others allow partial conversion. A partial term life insurance conversion may be considered when the policyowner wants permanent protection for one need but still wants temporary coverage for another.
For example, a household may have a long-term final-expense or dependent-support need alongside a mortgage need that will eventually end. Converting a portion could preserve permanent protection while leaving the balance as term coverage, subject to the contract.
Ask whether partial conversion is permitted, whether a minimum amount applies and what happens to the remaining term policy. Confirm whether riders can be converted or will terminate. Do not assume benefits attached to the old contract automatically transfer to the new one.
4. Know Why Health Changes Can Make Conversion Important
New individually underwritten coverage usually considers current age and health. A diagnosis, medication change or other medical history may affect eligibility or price. A contractual term life insurance conversion right can therefore be meaningful when the insured may no longer qualify for favorable new coverage.
This does not mean everyone with a health change should convert. The permanent premium must still fit the budget, and the available conversion product must support the intended need. Existing coverage, savings and other resources also belong in the analysis.
Avoid canceling the term policy while exploring alternatives. If new coverage is considered, keep the existing policy active until the new contract is approved, delivered, reviewed and in force. Replacement and carrier-specific requirements should be followed.
5. Understand Why the Premium Increases
People are sometimes surprised that term life insurance conversion produces a much higher premium. The converted policy is generally priced at the insured’s attained age, not the age when the original term policy was purchased. Permanent coverage also has a different cost structure because it is designed to remain in force longer and may accumulate cash value.
Ask for an illustration showing required premiums and both guaranteed and nonguaranteed values. A lower illustrated premium is not necessarily guaranteed to support the policy for life. Product type, funding pattern, charges and credited performance can affect durability.
Compare premiums with expected retirement income and other obligations. A benefit that looks attractive but cannot be maintained may not provide reliable long-term protection. Affordability should be tested under conservative assumptions.
6. Compare the Permanent Products Available
The conversion provision may limit which permanent policies are available. The carrier might offer whole life, universal life or another designated product. Available choices can change over time, subject to the contract and applicable rules.
The Florida Department of Financial Services explains that most term policies contain a conversion provision and that the permanent premium will be higher than the term premium. Florida’s consumer guidance also distinguishes term coverage from permanent cash-value coverage.
For each term life insurance conversion option, ask which premiums and death benefits are guaranteed, which values are nonguaranteed, what charges apply, whether premiums are flexible and what could cause the policy to lapse. Do not select a permanent product based solely on an attractive illustration.
7. Distinguish Conversion From Renewal
Renewal generally continues term coverage for another period, often at a higher premium based on the insured’s age. Conversion exchanges eligible term coverage for permanent coverage. These are different contractual choices.
The Florida life-insurance consumer guide notes that term coverage may renew without new evidence of insurability when the contract permits, but premiums increase with age. The same guide explains that a convertible term policy may be exchanged for whole life without new evidence of good health, subject to its terms.
A term life insurance conversion comparison should show the renewal premium, how frequently it may increase, the conversion premium and the intended duration of each option. A one-year renewal may provide temporary breathing room, but it may not solve a long-term need.
8. Compare Conversion With Applying for New Coverage
Someone who remains insurable may be able to apply for a new term or permanent policy from the existing carrier or another insurer. New underwriting could produce a different price or product selection. Approval is not guaranteed.
Term life insurance conversion may avoid new medical underwriting, while a new application may provide broader choices. The appropriate comparison depends on health, age, coverage needs, timing and affordability.
Never surrender or reduce existing coverage merely because a new application was submitted. Wait until the new policy is formally issued, delivered, accepted and active. Review any replacement notices and confirm that the new contestability and suicide-exclusion periods have been explained as applicable. Carrier and state compliance review is required.
9. Evaluate Partial Term Life Insurance Conversion
Partial term life insurance conversion can create a layered strategy. Part of the death benefit becomes permanent while the remainder continues as term insurance for its remaining period, if the contract permits.
This approach may fit someone who has both temporary and permanent obligations. A parent might want income-replacement coverage while children remain dependent but retain a smaller lifelong amount for a surviving spouse, final expenses or another continuing need.
Partial conversion does not automatically make the plan affordable or suitable. Confirm the premium, remaining term benefit, administrative rules and whether later conversion of the balance remains available. Obtain the carrier’s written explanation.
10. Review Beneficiaries and Ownership
A term life insurance conversion application is an appropriate time to confirm the owner, insured person and beneficiaries. Review primary and contingent beneficiaries, percentage allocations and current contact information.
Ownership changes can have legal and tax consequences. Beneficiary arrangements involving minors, trusts, divorce, businesses or estate planning may require qualified legal advice. Do not assume a will changes the policy’s beneficiary designation.
The new permanent policy should reflect the intended arrangement, but changes should not be made casually. Request carrier forms, complete them accurately and retain confirmation. Any trust or business ownership should be reviewed by appropriate professionals.
11. Examine Permanent-Policy Charges and Risks
Whole life, universal life, indexed universal life and variable universal life have different structures. A term life insurance conversion into one of these products should be evaluated using the actual contract and illustration.
Universal life may permit flexible premiums, but flexibility does not mean every payment pattern will keep the policy active. Charges, credited interest, loans, withdrawals and policy performance affect values. Indexed universal life generally credits interest using an external index formula, subject to a floor and limits such as caps, participation rates or spreads. It is life insurance, not a direct investment in the index.
Variable universal life involves investment risk and may lose value. Whole-life guarantees depend on required premiums and contract terms; dividends are generally not guaranteed. For every term life insurance conversion, distinguish guaranteed values from projections and confirm the insurer’s claims-paying ability.
12. Consider Surrender Periods, Loans and Lapse Risk
Permanent policies may impose surrender charges during early policy years. If the policy is canceled, the available surrender value may be less than premiums paid. This matters when term life insurance conversion is presented as easily reversible.
Policy loans accrue interest and generally reduce available value and the death benefit. Withdrawals can also reduce values. If a policy lapses with an outstanding loan, taxable income may result in some circumstances.
Ask for the surrender-charge schedule, loan provisions, current and guaranteed illustrations and the premium needed to support the intended duration. Ongoing monitoring is essential, particularly for flexible-premium policies with nonguaranteed elements.
[Insert the supporting article image here.]
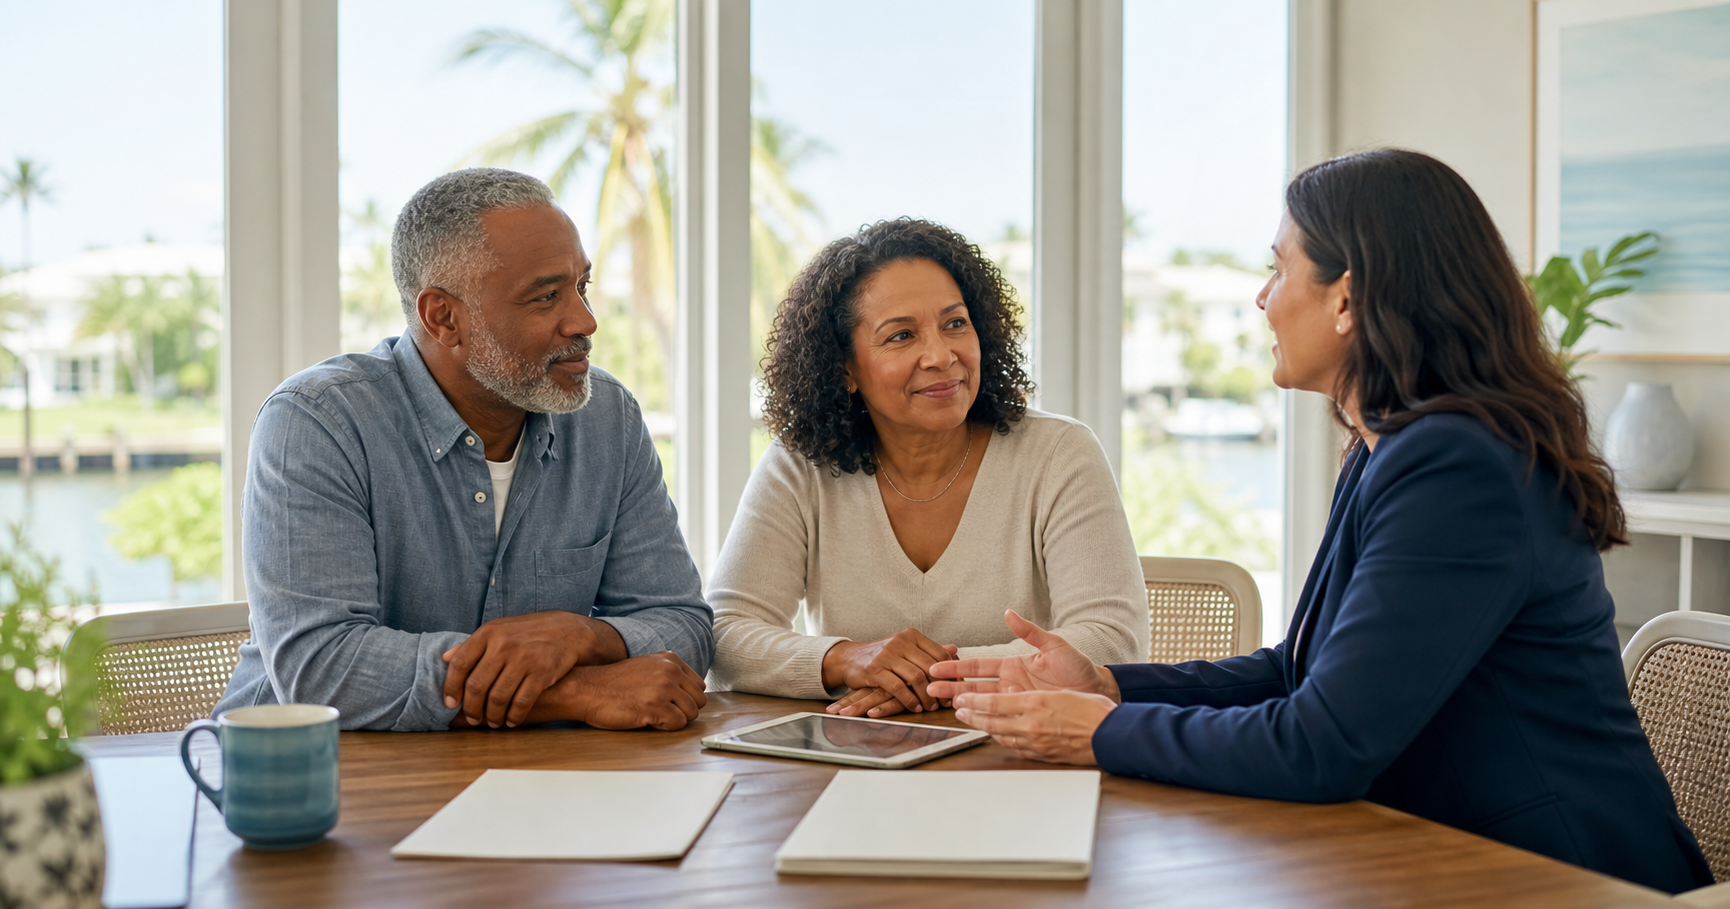
Image caption: Reviewing a term policy well before its conversion deadline gives a family time to compare costs, coverage needs and available permanent-policy choices.
A Hypothetical Conversion Decision
Consider Taylor and Morgan, a hypothetical composite couple in their early sixties. This is not a real client or promised outcome. Taylor purchased a 20-year term policy when their children were young. The level term is nearing its end, their mortgage is smaller and the children are independent, but Morgan would still experience a long-term income gap if Taylor died.
Taylor’s health has changed, making new underwriting uncertain. The couple requests written term life insurance conversion information nine months before the deadline. They compare converting the full amount, converting a smaller portion, renewing the term temporarily and retaining their other resources.
The couple does not assume conversion is automatically best. They examine premiums during retirement, policy guarantees, surrender charges and the smaller permanent need. Their process illustrates the value of beginning early and matching coverage to a defined objective.
When Term Life Insurance Conversion May Be Worth Exploring
Term life insurance conversion may deserve attention when health has deteriorated, a lifelong dependent needs support, a surviving spouse would face a persistent gap, estate liquidity is needed or business obligations remain.
It may also be useful when someone wants a permanent death benefit but cannot qualify for attractive new coverage. The contractual right can preserve access, although it does not guarantee that the available premium will be affordable.
The decision should be based on the actual policy, not general rules. Ask the carrier which products and amounts are available on the intended conversion date.
When Term Life Insurance Conversion May Not Fit
Term life insurance conversion may not fit when the underlying need has ended, the permanent premium is unsustainable or other resources adequately address the objective. Someone who remains healthy may also find different options through new underwriting, although approval and price are never certain.
Avoid converting solely because a deadline creates urgency. A deadline deserves prompt analysis, not a rushed purchase. Compare the benefit with the household’s present needs and retirement cash flow.
If no continuing need exists, allowing coverage to end may be reasonable. That decision should follow a review of beneficiaries, debts, dependents, spouse needs, final expenses and existing resources.
Questions to Ask the Carrier
Before exercising term life insurance conversion, request written answers to these questions:
- What is the final conversion date?
- Can the entire benefit be converted?
- Is partial conversion permitted?
- Which permanent products are eligible?
- What attained-age rate will apply?
- Is new evidence of insurability required?
- Which riders can be converted?
- What happens to remaining term coverage?
- Which values and premiums are guaranteed?
- What surrender charges, loans and policy charges apply?
- When must forms and the first premium be received?
- How will the carrier confirm completion?
Document the representative’s name, date and response. Retain illustrations, forms and confirmation with the policy records.
Tax Considerations for Term Life Insurance Conversion
The Internal Revenue Service states that death proceeds received by a beneficiary are generally not included in gross income. Interest and certain transfers can receive different treatment.
Term life insurance conversion can involve ownership, business or estate-planning questions that require individualized professional advice. Policy loans, modified endowment contracts, transfers and lapses may also create tax issues.
Do not describe a converted policy as universally tax-free. Tax law can change, and outcomes depend on the actual transaction and contract. Consult qualified tax and legal professionals.
Florida Consumer Protections and Resources
Florida consumers can use the Florida Department of Financial Services insurance resources to review life-insurance guides and contact the consumer helpline. Consumers should verify that the agent and insurer are licensed in Florida.
The department’s guidance recommends comparing plans, reading applications and policies carefully, distinguishing guaranteed from projected values and choosing premiums the policyowner can afford. These principles apply directly to term life insurance conversion.
State guidance does not replace the contract. Conversion rights are policy-specific, and disputes or unusual circumstances may require direct carrier, regulatory or legal review.
A Practical Conversion Timeline
Twelve months before the deadline, locate the policy and request written conversion information. Nine months before, identify the continuing coverage need and collect illustrations. Six months before, compare conversion, renewal and newly underwritten alternatives.
Three months before, narrow the options and resolve ownership, beneficiary and premium questions. At least several weeks before the deadline, submit any chosen term life insurance conversion paperwork and premium according to carrier instructions.
After completion, verify that the new policy is active and accurate. Store the contract securely, tell a trusted adult where it is and schedule annual reviews. Do not rely on an application alone as proof of coverage.
Common Term Life Insurance Conversion Mistakes
Common mistakes include assuming the right lasts until the term ends, waiting until the final week, converting the full benefit without recalculating the need and selecting a permanent policy based only on nonguaranteed projections.
Other errors include overlooking surrender charges, failing to test retirement affordability, ignoring loans and lapse risk, replacing coverage before new insurance is active and assuming riders transfer automatically.
A careful term life insurance conversion review avoids both extremes: allowing a useful right to expire without analysis and converting simply because the deadline exists.
The Bottom Line on Term Life Insurance Conversion
Term life insurance conversion can preserve access to permanent coverage without new evidence of insurability when the contract permits. That can matter after a health change or when a temporary need becomes a continuing one.
The feature still requires careful decisions. Confirm the deadline, eligible amount, product choices, premiums, guarantees, charges, surrender periods, loan provisions and lapse risk. Compare conversion with renewal, new underwriting and available household resources.
Most importantly, evaluate term life insurance conversion before urgency takes control. A well-documented review can show whether full conversion, partial conversion, another option or no change best matches the current need.
Visit the Gibbs Insurance life-insurance information page and learn more about Jay Cohen’s insurance experience. To review a conversion deadline or compare existing coverage, contact Gibbs Insurance & Financial Services and request a personalized policy review.
This article provides general educational information and is not individualized insurance, financial, investment, legal or tax advice. Conversion rights, products, underwriting, premiums, guarantees, charges and availability vary by policy, insurer and state. Carrier-specific, state-specific, legal and tax statements require appropriate professional review.